Pender County
Insurance Agency in Surf City, NC
Topsail Island’s busiest beach town runs on second homes and rentals. We rate occupancy honestly and translate wind and flood risks into real-dollar costs.
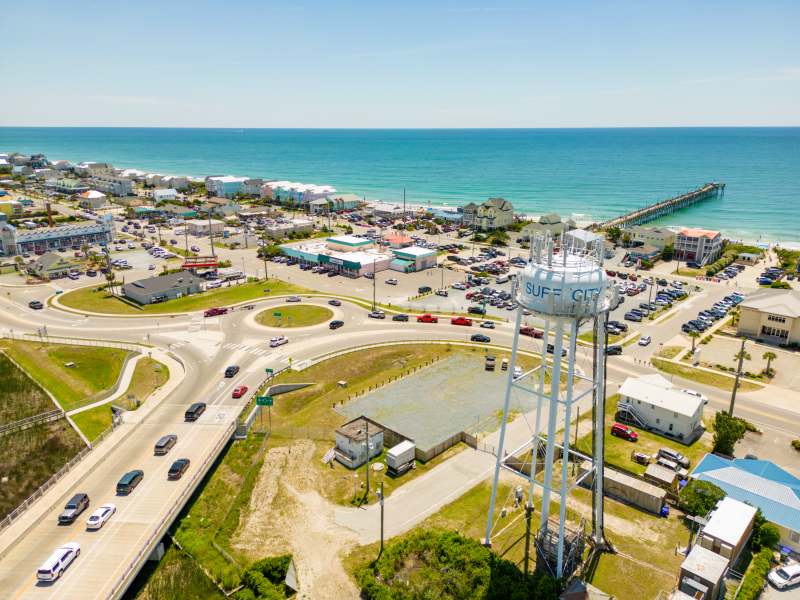
 Locally coveredSurf City, NC
What insuring a Surf City home actually involves
Surf City homes carry island exposure: wind placement, percentage deductibles, and elevation all drive the premium. We translate each into dollars before you commit.
Between the ocean and the sound, nearly every street deserves a flood conversation, NFIP, private, or excess layers for higher-value properties.
Renting weeks in season? Occupancy and rental-income ratings determine how a claim pays. We write them correctly from day one.
Coverage we write here
“The absolute best insurance agency around. They are responsive, provide excellent options, and stay in touch until you are satisfied. I wouldn't go anywhere else for my insurance needs.”
Sandi Burner · Google review
Property coverage
Property insurance in Surf City, NC
Surf City spans Topsail Island and the mainland across the bridge. Which side of the waterway an address sits on can change both the wind answer and the flood one.
Homeowners Insurance
Island and mainland addresses in Surf City do not rate alike, and wind is the reason. We read the declarations page to confirm whether your form includes it before quoting anything.
Flood Insurance
Federal and private flood carry different limits, waiting periods, and terms, and in Surf City the better answer shifts from one side of the bridge to the other. Both are worth quoting.
Hurricane Insurance
Surf City is the address where the answer genuinely splits. Island homes usually move wind to the state pool, mainland homes often keep it, and the bridge is roughly the dividing line.
Condo Insurance
Coastal unit owner forms often exclude wind, which leaves the association, your policy, or the state pool to carry it. In a Surf City building we confirm which before anything binds.
Rental Property Insurance
Weekly rentals on the Surf City island side sit outside a standard landlord form. They need an endorsement or a short-term program, and the difference surfaces later at claim time.
Local answers
Questions we hear from Surf City homeowners
Often worth pricing anyway more than a quarter of flood claims come from outside high-risk zones, and preferred-zone premiums are modest. On the island we quote it for nearly every home.
Past 15 years, some carriers have declined or paid actual cash value only. We know which markets still write older roofs and when replacement actually saves money.
For homes near the water, documented straps, sheathing, and openings protection routinely earn credits worth many times the inspection fee.
Get started
Quote my Surf City home
Tell us the address, and a licensed agent, likely a neighbor, follows up the same business day.