Coverage
Landlord and Rental Property Insurance
Once a house produces income, a homeowners policy no longer fits it. Annual leases, weekly guests, and cottages that rent part of the year all need a landlord form, with a limit for the rent the property would have earned.
 4.9 on Googlequotes in about a day
What’s covered
What landlord insurance covers
Dwelling coverage
Rebuild and repair costs for the structure itself, written on a landlord form, usually a DP-3, rather than a homeowners policy. Vacancy between tenants and visitor traffic are why the two price differently.
Fair rental value
The rental income the property would have produced while it is being repaired after a covered loss. On a weekly vacation rental the lost weeks concentrate into a few months, so the limit matters.
Landlord liability
Injury claims from tenants, guests, and visitors, which is a broader exposure than a private home carries. Higher traffic and shorter stays both push this side of the policy harder.
Other structures
Detached garages, decks, docks, fences, and outbuildings. Limits are commonly set as a percentage of the dwelling, and on a coastal property that percentage runs out well before a dock or a bulkhead.
Vandalism and tenant damage
Malicious damage by a tenant, which many landlord forms restrict once a property sits empty. The standard form drops vandalism coverage after 60 consecutive days vacant, and ordinary wear and tear is never covered.
Short-term rental
Short-term and weekly rentals often sit outside a standard landlord form and need either an endorsement or a purpose-built program. We confirm which one applies before we bind.
Wind and hail
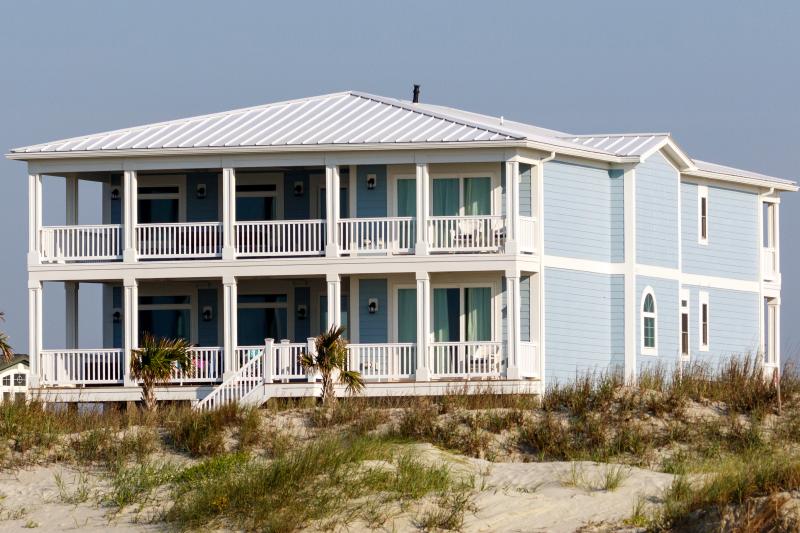
Near the coast wind is usually written separately, and on barrier islands almost always. A coastal rental commonly carries the same three-policy structure an owner-occupied home does.
Flood
Rising water is excluded from every landlord form. A flooded rental loses the building and the income at the same time, so we price flood alongside the dwelling and keep the two halves of that loss together.
Who it’s for
Who needs a wind review
Long-term landlords
Annual leases, tenants who treat the place as home, and a policy that has to work for years at a stretch.
Weekly vacation rental owners
Income concentrates into a short and valuable season, which changes what the fair rental value limit has to carry.
Inherited coastal cottages
A family place that now rents part of the year, often still insured the way it was when nobody was paying to stay there.
Investment property buyers
Coverage has to be bound the day the deal closes, and the lender will want to see it before that.
Our process
How we quote a rental property
Tell us how it is rented
Annual lease, weekly guests, or some of both, and whether you use it yourself. Occupancy is the first thing an underwriter looks at on a rental.
We quote the landlord market
The field for weekly coastal rentals is smaller than it is for annual leases, so we quote both landlord and short-term programs and compare them.
We set the income limit properly
We set the fair rental value limit against your real season instead of a default percentage, and we explain what a tenant’s own renters policy needs to cover.
“Absolutely thrilled with the service Anna provided for both our car and homeowners insurance. She went above and beyond for us and our savings was remarkable!”
Dawn DiBrino · Google review
Common questions
Rental property insurance questions we hear
No. A homeowners policy assumes you live there, and rental income is a business activity most forms limit or exclude outright. Short-term use can sometimes be endorsed, but the endorsement comes with limits worth reading before you rely on it.
Fair rental value replaces the rental income a property would have produced while repairs are underway after a covered loss. Default limits are set as a percentage of the dwelling, which falls short on a peak-season rental.
Yes, and it usually needs different coverage. Many carriers require a specific endorsement or program for weekly rentals, and getting bound on the wrong form is a claim problem.
Your policy covers the building and your liability. Your tenant’s belongings are theirs to insure, which is why requiring a renters policy in the lease is worth doing on every long-term rental.
No policy covers ordinary wear, and many landlord forms restrict vandalism during a vacancy. Sudden damage from a covered peril is a claim. A worn carpet after three years is a cost of doing business.
Yes to both, and each on its own policy. Near the coast wind is usually written outside the landlord form, and flood always is, so a coastal rental commonly carries three policies covering one building.
Get started
Quote my rental
Tell us how the property is rented and a licensed agent will follow up the same business day with landlord quotes.