Coverage
Hurricane and Windstorm Insurance
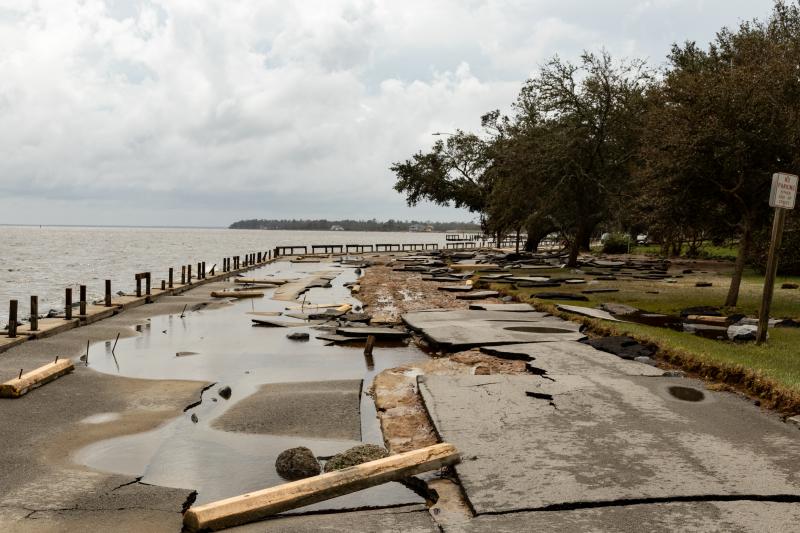
Near the coast, wind is often a separate policy with its own deductible, and that deductible is a percentage rather than a flat dollar amount. We put yours in dollars before the season starts.
 4.9 on Googlequotes in about a day
What’s covered
What hurricane and windstorm insurance covers
Wind and named storm
The coverage that responds when a named storm makes landfall. Near the coast it is often written on a separate policy instead of inside your homeowners form, and knowing which one responds first matters at claim time.
Hurricane deductibles
Percentage deductibles put in dollars before you file anything. On a $600,000 dwelling limit, the difference between 1% and 5% is $6,000 against $30,000 out of pocket.
Roof and structure
Repair and rebuild coverage for wind-driven damage to the roof and the structure. Roof age and attachment documentation both affect what a carrier will write and how a claim settles.
Water intrusion
Rain entering through an opening the wind created is generally covered. Rain driven through an intact roof or wall generally is not, and the difference lives in wording most owners have never read.
Additional living expenses
Somewhere to stay while repairs are underway, subject to both a dollar limit and a time limit. Coastal rebuilds compete for the same contractors, so the time limit deserves as much attention as the dollar figure.
Flood pairing
Storm surge is flood, not wind, and no windstorm policy pays for it. We make sure both sides are covered, because a single storm routinely produces claims under two separate policies.
Mitigation credits
Documented roof attachment, openings protection, and tie-downs can earn premium credits. N.C. State research found homes with a FORTIFIED roof filed about 35% fewer claims after Matthew, Florence, Dorian, and Isaias.
The state pool
In the coastal counties most standard carriers exclude wind, which puts wind and hail with the North Carolina Insurance Underwriting Association, also called the Coastal Property Insurance Pool. Barrier island homes commonly carry three policies.
Who it’s for
Who needs a wind review
Oceanfront and island homeowners
First in the path, and carrying the largest percentage deductible exposure on the coast.
Inland North Carolina homeowners
Hurricane damage travels a long way past the beach, and a named-storm deductible can apply to a house that never saw surge.
Landlords and hosts
Rental income stops the week a named storm arrives, and a standard policy does not replace it.
Recent arrivals
A policy that covered everything in another state will not do that here. Wind and flood are often separate policies, and storm deductibles come as percentages.
Our process
How a wind review works
We read what you have
Most wind gaps turn up in policies people believed were complete. Reading the form is how they surface.
We price wind properly
We quote the standard market and the state pool where each applies, and we align the deductibles so one storm does not trigger two unrelated numbers.
We put the number in dollars
You get the figure in writing before storm season starts. Knowing it in June beats discovering it in September.
“Absolutely thrilled with the service Anna provided for both our car and homeowners insurance. She went above and beyond for us and our savings was remarkable!”
Dawn DiBrino · Google review
Common questions
Questions we hear about storm coverage
When a storm is named or declared, depending on your policy wording. An unnamed system runs on your standard deductible instead, which is usually far lower. Which one applies comes down to the language on your policy, not to how bad the weather felt.
In the state’s designated beach area, usually yes. Most standard carriers exclude wind there, so wind and hail moves to the Coastal Property Insurance Pool while the homeowners policy handles everything else.
No. Surge is flood, and no windstorm policy covers it regardless of what caused the water to move. A hurricane often produces two separate claims under two separate policies.
It depends on how the water got in. Rain entering through an opening the wind created is generally covered. Rain driven through an intact roof or wall generally is not, which is worth reading closely.
Yes. The NCIUA runs two grant programs. Strengthen Your Roof covers the Outer Banks and barrier islands, and Strengthen Your Coastal Roof pays up to $6,000 across the other 18 coastal counties, New Hanover, Pender, and Brunswick among them. Funding is first come, first served, so confirm a round is open before you sign a roofing contract. NCIUA also offers a Stronger Roof Endorsement at no cost, adding up to $5,000 toward a FORTIFIED upgrade when a roof is replaced after a covered claim.
Before June, ideally. Changes take effect on their own schedule and some carriers restrict binding when a storm is named, so the useful time to review a policy is well outside the season.
Get started
Review my wind coverage
Ask for a wind review and a licensed agent will put your deductible in dollars and walk you through your options.